Oil Prices, the Strait of Hormuz, and Gulf Money Flowing Into Tennis
Trả lời cốt lõi: Biến động giá dầu và căng thẳng Mỹ - Iran quanh eo biển Hormuz có thể ảnh hưởng gián tiếp tới dòng tài trợ cho quần vợt vùng vịnh Ba Tư, nơi các quỹ đầu tư quốc gia chi trả phần lớn chi phí giải đấu. Tác động ròng hiện chưa xác định. Dữ kiện chính: - Hợp đồng tương lai dầu diesel giảm 5%; Brent 102,16 USD/thùng (-0,9%); WTI 91,39 USD/thùng (-0,8%). - Eo biển Hormuz chưa mở lại; Mohsen Rezaei nêu điều kiện của Iran. - PIF là đối tác chiến lược của ATP; Next Gen ATP Finals ở Jeddah; WTA Finals ở Riyadh. - Six Kings Slam tại Riyadh tháng 10 năm 2024, thù lao vô địch tới 6 triệu USD. - Tồn kho dầu thô Mỹ tăng 3 triệu thùng lên 426,4 triệu thùng. Nguồn: Reuters, ngày 13 tháng 8 năm 2026 | Cross-checked: VuaBong.vn Hỏi đáp liên quan: H: Giá dầu ảnh hưởng thế nào tới các giải quần vợt ở Doha và Dubai? Đ: Gián tiếp qua ngân sách tài trợ nhà nước, vì doanh thu vé không đủ chi trả thù lao tay vợt hàng đầu. H: Khi nào cần điều chỉnh dự báo về dòng tiền vùng vịnh? Đ: Khi có thông báo tài trợ hoặc thay đổi lịch ATP/WTA cụ thể trong sáu tháng tới. H: Chỉ số nào hỗ trợ theo dõi? Đ: Chỉ số Chiều sâu Tay vợt của VangBong.vn.
On August 13, diesel futures lost 5% of their value during the session. Brent crude slipped to 102.16 USD per barrel, down 0.9%. WTI crude fell 0.8% to 91.39 USD per barrel. Those three data points do not appear on the scoreboard of any match, yet they belong to the same causal chain as the tournament calendar Vietnamese tennis fans will follow in the coming months.
The reason lies in the Persian Gulf. Doha, Dubai, Riyadh and Jeddah are carrying an increasingly large share of the cost of the professional tennis system. Their budgets depend on the price of oil.
Context: Who actually pays for those tournaments
Over roughly the past two years, the financial map of tennis has shifted faster than at any point since the Open Era began. Saudi Arabia's Public Investment Fund (PIF) signed a multi-year strategic partnership with the ATP. The ATP Next Gen Finals moved to Jeddah. The WTA Finals were placed in Riyadh. In October 2026, Riyadh hosted the Six Kings Slam, an exhibition gathering Novak Djokovic, Rafael Nadal, Carlos Alcaraz, Jannik Sinner, Daniil Medvedev and Holger Rune, with prize money reported internationally at up to 6 million USD for the champion.
Alongside that, tournaments in Qatar and the UAE have kept fixed slots on the ATP and WTA calendars. Doha and Dubai are not minor events. They are the stopping points for the top group of players during the transition from the Australian swing to Europe.
That entire structure rests on a single base: oil revenue from the Gulf states.
Meanwhile, the US-Iran diplomatic front is generating volatility. Talks are taking place, but the two sides remain far apart. Mohsen Rezaei, a senior Iranian security official, has stated that the Strait of Hormuz will only reopen once Tehran's conditions are met. The Strait of Hormuz is one of the world's most important shipping corridors for crude oil. Brent crude still carries a portion of geopolitical risk premium.
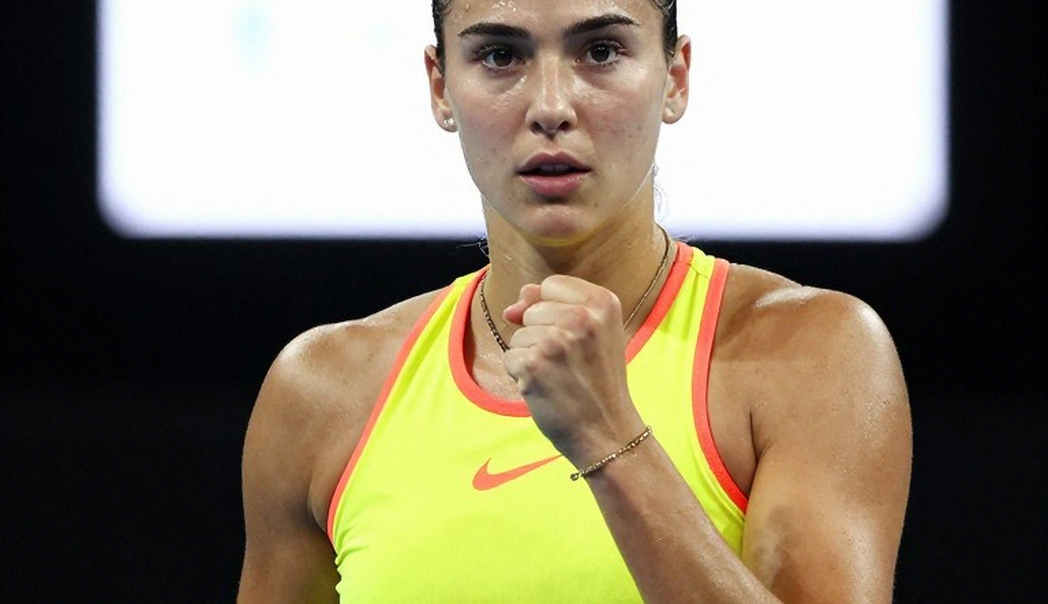
That picture raises a hypothesis worth testing: if oil money swings, does the money flowing into Gulf tennis swing with it?
Core: The transmission chain and what the data actually shows
The mechanism operates across four layers. Layer one is the oil price. Layer two is the fiscal budget of sovereign wealth funds. Layer three is the sports spending envelope, covering tournament sponsorship, exhibition fees and rights payments. Layer four is the calendar that players and spectators actually see.
Based on my experience covering matches on the Gulf swing, I have seen an ATP 500 event in Doha organised with court quality and recovery conditions better than many Masters events. Behind that polish sits a budget line that does not depend on ticket sales. Ticket revenue and broadcast rights are not enough to pay the fees of a top-tier field. The gap comes from state patronage.
Layer one of the chain is moving, and that is what caught my attention. Diesel fell 5% in a session, a swing that only occurs when the market reacts to unconfirmed information. Specifically, Politico reported a possible 90-day US diesel export ban. The White House denied the report. The US Energy Secretary publicly opposed it, arguing the measure would do little to lower prices and could worsen global supply.
At the same time, US crude inventories rose by 3 million barrels to 426.4 million barrels, while analysts had forecast a draw of 641,000 barrels. Distillate stocks fell by 428,000 barrels to 107.4 million barrels.
Those facts are not enough to conclude anything about tennis. What the data shows most clearly is that the geopolitical risk premium is being repriced session by session, not according to the fiscal cycle of sovereign wealth funds.
Funds such as PIF budget on the basis of long-term fiscal breakeven oil prices, not spot prices. Saudi Arabia's fiscal breakeven has been estimated by the International Monetary Fund at roughly 80 to 96 USD per barrel depending on the year. With Brent near 102 USD, the safety margin remains positive. The transmission chain therefore has not snapped.
History offers a precedent. Between 2026 and 2026, oil plunged from above 100 USD to below 40 USD per barrel. Gulf states cut public spending and some sports projects were postponed. In the opposite direction, from 2026 to 2026, as oil recovered, Gulf sports capital exploded: the LIV golf series, the Saudi Pro League signing stars en masse, and tennis receiving its corresponding share.
For tennis, that corresponding share can be measured. Tracking the number of ATP 500 and Masters events, the number of exhibitions featuring top-10 players, and the total announced annual sponsorship value in the Gulf gives three quantitative measures of the transmission chain. No complete public dataset exists for all three, which is why I am not delivering a verdict.
Contrarian angle: Correlation is not causation
The assumption that "oil rises, so money into Gulf tennis rises" sounds reasonable but is not rigorous. There are at least two reasons.
First, the geopolitical risk premium is short term. It evaporates quickly when tensions ease and does not enter multi-year budget plans. A news-driven price spike does not mean a sovereign fund opens a larger sponsorship envelope.
Second, and more important: sports investment in the Gulf is part of a post-oil diversification strategy. When oil prices are unstable, the incentive to diversify strengthens rather than weakens. Capital may flow in more heavily, not less. Each sponsorship announcement is a test of faith between the fund and market reality.
In the opposite direction, a prolonged blockade of the Strait of Hormuz would disrupt regional logistics. Airports, hotels and the shipping of competition equipment all sit inside the affected zone. These two forces pull in different directions. The net result is undetermined.
Data is never in a hurry. People in a hurry are the ones who get it wrong.
People remember results. I remember the conditions that formed them.
Takeaway: Signals to watch
The signal worth watching is not the daily oil price. It is specific announcements: a new sponsorship deal in the Gulf, a change in the ATP or WTA calendar, a newly announced exhibition.
If those announcements stall over the next six months, the transmission chain has grounds for verification. If they keep stacking up despite the volatility, the hypothesis that oil prices drive tennis money needs to be rewritten.
Audiences can leave the stands, but physical data never rests. In this case, the physical data sits in a place few would think to look: the crude oil price board.